
Current Equity Exposure
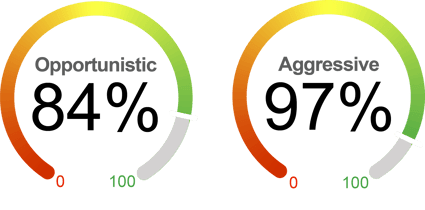
We employ two distinctive dynamic market exposure models in our strategies: one tailored for growth-focused investors seeking aggressive opportunities and another designed for those with a more defensive approach, prioritizing capital preservation. *For illustrative purposes only.
U.S. equities delivered a mixed and increasingly uneven performance in the third quarter of 2026, as investors balanced resilient economic growth, strong corporate earnings, and continued AI-related investment against elevated inflation, rising Treasury yields, and a more hawkish Federal Reserve. July began with a rotation away from richly valued technology and semiconductor stocks toward more defensive sectors. Concerns about excessive AI infrastructure spending and future profitability weighed on technology shares, while higher energy prices renewed inflation concerns and pushed Treasury yields higher, adding pressure to growth-oriented sectors.
As the quarter progressed, strong corporate earnings helped restore market momentum. August saw equities advance, led by technology, as continued AI investment and NVIDIA’s strong earnings report supported sentiment. However, rising long-term yields remained a headwind as investors assessed elevated inflation, a large fiscal deficit, and substantial private investment needs. Treasury’s expansion of its longer-dated securities buyback program provided temporary relief, but did little to resolve the underlying pressures on yields. At the end of the month, Fed Chair Warsh’s more hawkish-than-expected remarks at Jackson Hole reinforced the central bank’s commitment to its 2% inflation target and increased expectations for further monetary tightening.
By September, market performance became more divided as the Fed raised interest rates and Treasury yields climbed further. Continued AI enthusiasm and strong earnings expectations supported technology stocks, while higher rates weighed on small-cap stocks, equal-weight indexes, and broader market participation. By late September, only 41% of S&P 500 stocks were trading above their 200-day moving average, down from 75% over the summer. The U.S. 10-year Treasury yield reached 5.304% at month-end, its highest level since May 2002, increasing valuation pressure and reinforcing the higher-for-longer interest-rate backdrop.
Despite these headwinds, the underlying economic and corporate backdrop remained supportive. Second-quarter earnings were broadly strong, with positive surprises across sectors helping offset concerns about stretched valuations and financing costs. Labor market data showed signs of softening earlier in the quarter, although subsequent economic and employment resilience supported the Fed’s willingness to tighten policy. AI-related investment remained an important driver of earnings expectations and market leadership, even as investors became more selective about the potential returns from substantial capital spending. Inflation, fiscal pressures, and uncertainty around monetary policy continued to create risks for the broader equity market.
With this backdrop, the outlook for U.S. equities remains moderately constructive but selective. We continue to see opportunities supported by resilient growth, healthy corporate earnings, and AI-related productivity gains, while remaining mindful of narrowing market breadth, stretched valuations, and higher interest rates. We maintained our equity exposure at 84% in our defensive, tailored approach.
What's Driving the Markets?
Market Breadth: Despite the S&P 500's relatively resilient performance, market breadth has narrowed materially after Fed Chair Warsh's hawkish commentary at Jackson Hole and the Fed's rate hike at its September meeting. As of September 29, only 41% of S&P 500 stocks were above their 200-day moving average, compared with 59% in late May and 75% over the summer. The S&P 500 equal-weighted index lost about 4.5% in September while the cap-weighted S&P 500 was roughly flat. Higher energy prices and rising yields have a greater impact on rate-sensitive and economically cyclical stocks, as higher long-term yields increase financing costs and put pressure on equity valuations. At the same time, AI and mega-cap tech companies have benefited from strong earnings expectations and substantial cash flow, allowing them to deliver relatively strong performance despite higher rates.
Resilient Macroeconomic Fundamentals: The macro backdrop remains resilient. The ISM Manufacturing Index has held in expansion territory for eight straight months. Retail sales increased 1.2% in August with broad-based strength and non-store retailers leading the gain. Although economic growth cooled modestly, real GDP grew 2.2% in the second quarter after expanding 2.5% in the first quarter. Consumer spending was the most significant contributor, followed by nonresidential fixed investment and exports. The labor market also showed resilience in August, with payroll employment rising by 162,000, exceeding expectations. Meanwhile, recent inflation data was in line with expectations. The Fed's preferred inflation measure, Personal Consumption Expenditures (PCE), increased by 0.3% in August, leaving the year-over-year rate unchanged at 3.4%.
Fed Policy: At its September meeting, the FOMC hiked its policy rate by 25bps to 3.75%-4%. The decision was unanimous, and a majority of committee members expect at least one more rate hike by year-end. Policymakers also slightly raised their growth projection and lowered their unemployment rate forecast from 4.3% to 4.1%. Persistent inflation and surging energy prices, driven by the renewed escalation in the Middle East conflict, were the main contributors to the rate-hike decision. At the same time, the real GDP growth estimate in the third quarter is 3.7% (Atlanta Fed’s latest GDPNow estimate), while nonfarm payrolls increased by 162k in August, both beating consensus expectations. In our opinion, our baseline forecast expects the policy rates to remain unchanged for the rest of the year. The Iran war, a supply-side shock, has been one of the main drivers of persistent inflation. Supply-side shocks, however, are not responsive to monetary policy tightening.
.
By the Numbers
Valuation
|
Sentiment
|
Technical
|
Macroeconomic
|